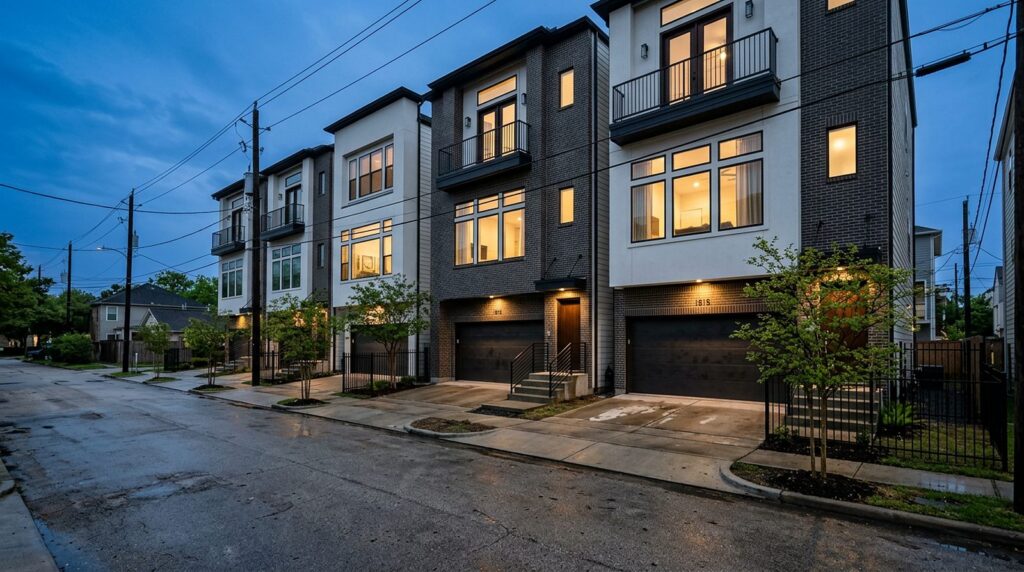
Buying in Houston
Written July 22, 2026. The market numbers below come from the Houston Association of REALTORS® MLS reports through June. Fannie Mae’s August 3 condo changes are now in effect, and the January 4, 2027 reserve change is still ahead.
Houston’s single-family market spent the first half of 2026 doing a very boring thing: holding steady. Sales up modestly, prices flat, inventory balanced. Meanwhile one segment quietly went the other way.
I’m Eddie Weir, a REALTOR® with REMAX Signature in Greater Houston, and I read the segment data every month because the metro average hides more than it reveals. Townhomes and condominiums are the one Houston property type losing ground. Sales fell 9.3% in June 2026 while detached sales rose 3.5%. Through the first half of the year, attached-housing closings ran about 7% below 2025 while detached ran about 1% above, and the segment is carrying roughly eight months of inventory against under five for detached.
But “the condo market is crashing” would be the wrong conclusion, and I want to be careful here, because the price data doesn’t actually say that. What’s happening is more specific, and Fannie Mae’s stricter condo rules took effect for loan applications dated on or after August 3, 2026. One more change, a 15% minimum reserve allocation, applies from January 4, 2027.
Are Houston townhome and condo prices falling?
Volume is falling. Prices are bouncing around, which is a different thing and worth separating.
Here is what HAR MLS actually reported month by month this year for the townhome-and-condominium segment:
| Month | Closed sales | Sales YoY | Median price | Median YoY | Months of inventory |
|---|---|---|---|---|---|
| January | 269 | –25.9% | $185,000 | –11.9% | 7.6 |
| February | 299 | –7.4% | $240,500 | –3.4% | 8.1 |
| March | 402 | +1.8% | $220,000 | –4.3% | 8.2 |
| April | 450 | 0.0% | $230,000 | +7.0% | 8.3 |
| May | 464 | –4.3% | $230,000 | +3.6% | not published |
| June | 439 | –9.3% | $215,000 | –6.5% | not published |
Down 11.9% in January, up 7.0% in April, down 6.5% in June. That is not a price trend. That is a mix effect on a shrinking transaction count — when a segment only closes 400-odd sales a month across everything from a 1970s garden condo off Westheimer to a new Heights townhome, the composition of what sold moves the median more than the market does.
The Greater Houston Partnership’s economic research team described the same dynamic precisely: for townhomes and condos, “Sales are down and listings are up, meaning buyers have more options and properties are taking longer to move,” and yet prices in some months are still increasing, “suggesting buyers who remain in the market are gravitating towards newer, larger, better-located, or higher-quality properties.”
The number I’d actually watch isn’t price. It’s supply. Townhome-and-condo inventory ran 7.6 to 8.3 months from January through April, versus 4.7 to 4.9 months for detached over the same stretch — roughly 60 to 70% looser. A year earlier, HAR flagged this segment’s 8.0-month supply as the highest since September 2011. That gap, not the median, is where a buyer’s negotiating leverage comes from.
Why is the attached-housing segment so much softer than detached?
Four reasons, and only one of them has anything to do with the buildings themselves.
1. Carrying costs went up faster than prices
Houston has the third-highest share of homeowners paying HOA or condo fees of any large U.S. metro — 55.3%, per LendingTree’s analysis of Census data published in March 2026. The median Houston fee is a modest $105 a month, but 19% of Houston HOA-payers are above $500, and 82% of HOA residents nationally reported fee increases over the past three years, with 44% calling the increases significant.
The main driver is insurance. Texas homeowners insurance rate filings rose an average of 10.8% in 2022, 21.1% in 2023, and 18.7% in 2024 before slowing to 4.3% in 2025, per the Texas Department of Insurance. The Dallas Fed found the median Texas homeowner paid 60% more for home insurance in 2024 than in 2019, against 30% nationally. Associations buy insurance too — and when a master policy premium doubles, it comes out of dues or a special assessment.
A useful rule of thumb when you’re comparing options: every $100 a month in HOA dues has roughly the same effect on what you qualify for as about $10,000 more in purchase price. A $250,000 condo with $450 monthly dues costs about the same each month as a $295,000 house with no dues. Put the other way, a buyer who qualifies for a $250,000 house qualifies for about a $205,000 condo at those dues.
2. Texas requires nothing on reserves — so lenders stepped in instead
After Surfside, Florida imposed milestone structural inspections and mandatory structural-integrity reserve studies on condominium associations. Texas did not. There is no state requirement for a reserve study, no minimum reserve funding level, and no structural inspection mandate for Texas condominiums or POAs. The 2025 legislative session’s condo bill was a transparency measure — online posting of governing documents, expanded management-certificate disclosure — not a reserve or inspection mandate. Texas law requires disclosure of reserves “if any,” and a blank line is legally compliant.
That vacuum didn’t stay empty. The federal mortgage market filled it, which brings us to the part with a date on it.
3. Condo financing got meaningfully stricter on August 3
Fannie Mae issued Lender Letter LL-2026-03 on March 18, 2026, and it changes how nearly every Houston condominium project gets underwritten:
- The Limited Review is retired. Established projects that used to qualify for the lighter review must now go through a Full Review, or a waiver where one applies. Mandatory for loan applications dated on or after August 3, 2026.
- Reserve studies must be funded at the highest recommended level. Lenders can no longer accept the baseline funding method, which allowed reserve balances to approach zero. Also effective August 3, 2026.
- Minimum replacement reserve allocation rises from 10% to 15% of annual budgeted assessment income — effective January 4, 2027.
- The master policy per-unit deductible is capped at $50,000 — effective July 1, 2026, so already in force.
Those sit on top of standing rules that already disqualify a project: outstanding critical repairs affecting safety, soundness, structural integrity, or habitability; an active evacuation order; unfunded repairs exceeding $10,000 per unit needed within 12 months; more than 15% of units 60-plus days delinquent on assessments; and single-entity ownership above 20% in projects of 21 or more units. A project flagged “Unavailable” in Fannie’s Condo Project Manager is ineligible regardless of anything else.
Here is what that means in a real transaction. If your buyer’s lender determines the project doesn’t qualify, the loan can’t be sold to Fannie Mae — and your buyer’s options narrow to a portfolio “non-warrantable” condo loan at a higher rate with a bigger down payment, a separately approved FHA or VA project, or cash. A law-firm client alert on the change put the consequence bluntly: lenders unable to sell those loans “can restrict buyers’ access to financing and, in turn, depress property values and limit marketability.”
One frustrating detail for buyers: Fannie’s ineligible-project list is not public. You cannot look up a building. You have to ask the lender to run it, and ask the association directly for the reserve study, the budget, and any pending assessments.
4. In Houston specifically, cheap detached houses compete head-on
This is the mechanism most national commentary misses, and it’s the most Houston thing on this page.
In June 2026, Houston closed 1,825 detached single-family homes under $250,000 — 153 under $100,000, 191 between $100,000 and $150,000, and 1,481 between $150,000 and $250,000. The entire townhome-and-condo segment closed 439 units at all price points combined, at a median of $215,000. Detached sales in that band were growing double digits while attached sales fell.
In most large metros, an entry-level buyer choosing between a condo and a detached house isn’t really choosing — the house costs 40% more. In Houston it’s a live decision, because our lot-size reforms produced an enormous amount of small-lot, fee-simple housing. The city cut the minimum lot size inside Loop 610 from 5,000 to 3,500 square feet in 1998 and extended it citywide in 2013; researchers count roughly 80,000 small-lot homes built since, and more than 34,000 townhouses built in the city between 2007 and 2020 alone. When a buyer can get a yard, no shared insurance, and no association for the same money, a lot of them do. That supply story is the same one behind why Houston homes stay relatively affordable.
Check the property and the project.
We can organize the association, insurance and financing questions before your contract deadlines.
Book a 30-minute callWhat should I ask for before buying a Houston condo or townhome?
Texas gives you real statutory rights here, and they differ depending on how the property is legally organized — which the listing photos will never tell you.
If it’s a condominium (Texas Property Code Chapter 82), the seller must give you a current copy of the declaration, bylaws, association rules, and a resale certificate issued within the previous three months. That certificate has to include the current operating budget plus specific items: current assessments and frequency, amounts the seller owes, capital expenditures approved for the next 12 months, the amount of reserves and any portion designated for a specific project, unsatisfied judgments and pending lawsuits, insurance coverage, known violations, and all transfer fees. The association has 10 days to produce it after a written request. Ask what it charges, because the certificate has to list its transfer-related fees.
And there’s a right most buyers never hear about: under §82.156, if those documents weren’t delivered before you signed, you may cancel the contract before the sixth day after you receive them — in writing, hand-delivered or by certified mail, with all payments refunded and no penalty.
If it’s a fee-simple townhome in a POA subdivision (Chapter 207), the association has 10 business days to deliver the restrictions, bylaws, rules, and a resale certificate prepared within the prior 60 days, covering assessments, pending special assessments, capital expenditures, reserves, the budget, litigation, insurance, and known violations. Fees are capped at $375, or $75 for an updated certificate — and the association may not charge at all if it misses the deadline.
Read the reserve and pending-assessment lines first. In a state that requires no reserve study, a healthy reserve is a signal that the board is competent, and a thin one is a signal that a special assessment is somebody’s future — possibly yours.
One data caveat worth knowing
HAR reports townhomes and condominiums as a single combined statistic. A fee-simple three-story townhome in EaDo and a 1980s garden condo off the Southwest Freeway are averaged into the same median — and HAR does not publish a methodology note saying whether mid- and high-rise condominiums are folded in. So treat the segment number as directional, not as a valuation for any specific building. That’s exactly why I pull building-level comps rather than quoting the segment median to a client.
What this means if you’re buying
This is the best negotiating position attached-housing buyers have had in Houston in years — eight months of supply, longer marketing times, and less competition. Use it, but do the homework the segment demands:
- Get the project pre-checked before you go under contract. Ask your lender to run the association through Fannie’s Condo Project Manager early. Finding out at day 18 that a project is ineligible is an expensive way to learn.
- Ask for the reserve study, the last two years of budgets, and minutes. Minutes are where special assessments get discussed before they get voted.
- Underwrite the dues, not just the price. Ask what dues have done over three years, not just what they are today.
- Ask what the master policy covers and what its deductible is — and what your separate unit policy would need to carry.
- Compare honestly against a detached house at the same monthly cost. In Houston that comparison is real, and sometimes the townhome still wins on location, lock-and-leave convenience, or a neighborhood you couldn’t otherwise afford. Just make it a decision instead of an assumption — and if new construction is on your list, new construction versus resale covers the other side of that trade.
- If you’re buying it as a rental, run the dues through the return math first. Association fees change a cash-flow model more than most investors expect — see Houston cash-flow rental markets.
If the search is broader than one building, the buyer guide and mortgage preapproval pages cover the sequence, and the Houston home search will show you both property types side by side.
Buying a condo in Houston: what to check before you commit
A condo purchase includes the unit and a share of responsibility for the building. Before you decide, review the association’s finances, insurance, rules, and your lender’s requirements alongside the price and the inspection.
Start with the association documents
Ask for the declaration, bylaws, rules, current resale certificate, operating budget, balance sheet, and insurance summary. Texas Property Code Section 82.157 addresses resale documents, subject to its exceptions. TREC’s Condominium Resale Certificate, Form 32-5, collects the association’s financial and other disclosures. Section 82.156 gives the cancellation right I covered above. Have a real estate attorney explain how it and any other document-delivery rights apply to your contract, since the timing depends on the documents and the contract. Texas statute · TREC resale certificate. Sources checked October 25, 2026.
HOA dues: ask what is included
Read the budget and governing documents to learn which costs the association pays and which remain yours. Ask specifically about water, trash, building insurance, exterior maintenance, elevators, parking, amenities, and management. Do not assume an item is included because a different building includes it.
Build your monthly comparison from the mortgage, property taxes, unit-owner insurance, association dues, utilities you pay separately, and any assessment installment. Request the current dues schedule and any approved increase. A lower purchase price can still come with a higher total monthly obligation.
Reserves and special assessments
The resale certificate identifies approved capital expenditures for the next 12 months, capital reserves, unpaid assessments, and pending litigation. Those disclosures give you a starting point for questions; they are not a guarantee that future costs will stay flat. TREC Form 32-5.
Ask for the latest reserve study, if one exists, recent board minutes, and a schedule of major repairs. Compare the reserve balance with planned roof, elevator, plumbing, garage, and exterior work. Ask whether the board has discussed a special assessment that has not yet been approved, and have the contract address who pays any known assessment. This is a due-diligence checklist, not a claim that every Texas association must have a reserve study.
HO-6 insurance and the master policy
Your condo policy and the association’s master policy serve different purposes. Texas Department of Insurance explains that condo insurance covers personal property and the unit’s interior, with liability and additional living-expense protection. HUD’s condo documentation checklist separately identifies unit coverage, commonly called HO-6, and master hazard insurance. TDI home insurance guide · HUD insurance documentation.
Give both policies and the association documents to your insurance agent. Ask where the master coverage stops, which interior improvements you must insure, what deductibles could affect you, and whether loss-assessment coverage would respond to the building’s particular risks. Obtain a separate flood-coverage review. Most home policies exclude flood damage; neither a master-policy summary nor a condo listing establishes that your belongings are covered for flooding.
Can you use FHA or VA financing?
For FHA financing, HUD allows eligible units in approved projects and, in some unapproved projects, a Single-Unit Approval route. Search the exact project in HUD’s condominium lookup, then ask your lender to confirm the project, phase, status, and unit eligibility. An absent project listing is a reason for a lender review, not an automatic promise of approval or rejection. HUD condominium guidance.
VA’s purchase-loan guidance permits a condo in a VA-approved project. Ask your lender to check VA acceptance and any conditions for that specific development. FHA approval and VA approval are separate checks. Project approval also does not replace your own loan qualification. VA purchase loans · VA condo appraisal requirements.
Rental caps and your future plans
If you may rent the unit later, request the actual leasing provisions before buying. Ask about rental caps, waitlists, minimum lease terms, short-term rental restrictions, application procedures, and fees. Have the association identify the controlling document and have an attorney resolve questions about interpretation or enforceability. A current tenant in another unit does not establish permission to lease yours.
High-rise or garden-style: use a building checklist
| At a high-rise | At a garden-style or low-rise property | At either property |
|---|---|---|
| Review elevator service, emergency access, move-in reservations, garage access, and the maintenance of shared systems. | Review roofs, exterior stairs or walkways, drainage, parking, and responsibility for shared grounds. | Confirm which features actually exist, who maintains them, and how repairs are funded. Inspect the unit and review building records. |
For flood due diligence, check the property’s FEMA map designation separately from its reported flood history. Ask about the garage, ground-floor equipment, elevators, access routes, prior water damage, and repairs. A unit’s floor number alone does not answer those questions. Have your insurance agent address the unit and the common areas rather than assume an upper floor removes the need for a flood review. HUD’s checklist includes flood-map and applicable flood-insurance documents.
Think about resale before buying
Ask for recent comparable units in the same building or a clearly comparable project, including their dues, condition, financing issues, and time to receive an offer. A combined townhome-and-condo statistic can conceal differences between buildings. I’ll help you assess the evidence for the property you are considering rather than attach an unsupported citywide resale timeline to it.
Still deciding between a townhome and a detached house? Start with Townhome vs. single-family home in Houston.
Bring the unit address and the association documents you have, and we can organize the questions for the lender, insurer, association, and attorney. Book a 30-minute call.
What this means if you’re selling
Three things, in order of how much they matter.
First, price to the current segment, not to 2022. With eight months of supply, a townhome priced on hope sits — and in Houston, sitting means competing against 1,825 detached houses a month in your price band. Start with a free valuation for your address, then read how to price a Houston home to sell — the discipline matters more here than in the detached market, not less.
Second, get your association’s paperwork in order before you list. If the project has a thin reserve, a pending assessment, or a deferred repair, that is going to surface during your buyer’s underwriting anyway, and since August 3 it surfaces under a stricter review. Knowing in advance lets you price for it or address it, instead of losing a contract at day 25.
Third, widen the buyer pool where you can. If the project is FHA- or VA-approved, say so in the listing. If it is genuinely non-warrantable, we market to the buyers who can actually close — and price accordingly. That’s a strategy conversation, not a reason to panic.
Frequently asked questions: Houston townhomes and condos
Are Houston condo prices dropping in 2026?
Volume is down more clearly than price. Townhome and condo sales fell 9.3% year over year in June 2026 with a median of $215,000, down 6.5% — but the median was up 7.0% in April and 3.6% in May. On roughly 400 monthly sales spanning wildly different property types, the median swings on what happened to sell. The more reliable signal is inventory: about eight months of supply versus under five for detached homes.
What is a non-warrantable condo?
A condominium project that doesn’t meet Fannie Mae or Freddie Mac eligibility standards — typically because of outstanding critical repairs, insufficient reserves, high delinquency among owners, litigation, an evacuation order, or too much single-entity ownership. Loans on non-warrantable projects can’t be sold to the agencies, so buyers usually need a portfolio loan at a higher rate with a larger down payment, or cash.
What changed for condo buyers on August 3, 2026?
Fannie Mae retired the Limited Review process for established condominium projects. Loan applications dated on or after that date require a Full Review or an applicable waiver, and lenders must use the highest recommended reserve allocation from a project’s reserve study rather than the baseline funding method. A separate change raises the minimum replacement reserve allocation from 10% to 15% effective January 4, 2027.
Does Texas require condo associations to do reserve studies?
No. Texas has no statutory reserve study requirement, no minimum reserve funding standard, and no structural inspection mandate for condominiums or property owners’ associations. Texas law requires disclosure of reserves “if any” on the resale certificate — which means a blank reserve line is legally compliant. That is precisely why federal lending standards have become the practical backstop.
How long does a Texas condo association have to provide a resale certificate?
Ten days after receiving a written request, for a condominium under Chapter 82. Ask what it charges, because the certificate has to list its transfer-related fees. For a townhome in a POA subdivision under Chapter 207, it’s 10 business days, the certificate must have been prepared within the prior 60 days, the fee is capped at $375 (or $75 for an update), and the association may not charge a fee at all if it misses the deadline.
Can I cancel a Texas condo contract if I get the documents late?
For condominiums, yes. Texas Property Code §82.156 lets a purchaser cancel before the sixth day after receiving the declaration, bylaws, rules, and resale certificate if they weren’t delivered before the contract was signed. Cancellation must be in writing, hand-delivered or sent by certified mail, and all payments made before cancellation must be refunded without penalty.
Is a Houston townhome the same as a condo?
Not legally, and the difference matters. Many Houston townhomes are fee simple — you own the land and the structure — and fall under POA rules in Chapter 207. Others are built under a condominium regime, so they look like townhomes but function legally like condos under Chapter 82, with different disclosure timelines, a different cancellation right, and different lender project review. The deed and the dedicatory instruments decide which, not the listing label.
Should I buy a townhome or a house in Houston?
Compare total monthly cost, not sticker price — roughly, every $100 of monthly dues affects qualification about like $10,000 of purchase price. Houston is one of the few big metros where a detached home under $250,000 is a genuine alternative, and 1,825 of them sold in June alone. The townhome still wins for many buyers on location, maintenance, and lock-and-leave living. Just make it a real comparison.
The bottom line
Houston’s townhome and condo market isn’t collapsing. It’s thinning — fewer transactions, more standing inventory, and a widening gap between the projects that are easy to finance and the ones that aren’t. Rising association costs and a state that regulates almost nothing about reserves left the federal mortgage market to enforce the standards, and since August 3 that enforcement has been tighter.
For a prepared buyer, that’s opportunity: real leverage, in a segment most people are ignoring. For a seller, it’s a reason to get the association’s paperwork straight before the sign goes in the yard. For everyone else, it’s a reminder that “the Houston market” is not one thing.
Starting your search? Read my buyer guide.
Plan the condo or townhome search.
Bring your candidate properties, budget and timing. We can discuss the documents and professional answers to gather.
Book a 30-minute callAbout Eddie Weir
I’m Eddie Weir, a top 1% REALTOR® with REMAX Signature in Greater Houston. I hold the ABR (Accredited Buyer’s Representative) and LUXE designations and bring a corporate analytics and strategy background to residential real estate. I work with buyers, sellers, and investors across Harris, Brazoria, Fort Bend, and Montgomery counties, and I read the segment data every month so my clients aren’t making decisions off a metro average. More about how I work.
“Texas requires almost nothing of a condo association’s reserves. So the mortgage market became the regulator — and on August 3 it raised the bar.”
— Eddie Weir, REALTOR®, ABR, LUXE | REMAX Signature
Sources: Houston Association of REALTORS® MLS monthly housing reports, January–June 2026, including the townhome/condominium section and the single-family sales-by-price-segment table; Greater Houston Partnership, Monthly Update: Home Sales; Fannie Mae Lender Letter LL-2026-03 (March 18, 2026); Fannie Mae Selling Guide B4-2.1-03, Ineligible Projects and B4-2.2-02, Full Review Process; Whiteford, Taylor & Preston client alert on the 2026 project-standards changes; LendingTree HOA fee study (March 2026); Texas Department of Insurance, Texas homeowners insurance market overview; Federal Reserve Bank of Dallas, Southwest Economy (April 2026); Texas Property Code §82.157, §82.156, and §207.003; Pew Charitable Trusts on Houston lot-size reform and Mercatus Center, “Learning from Houston’s Townhouse Reforms”.
First-half segment comparisons are my own calculations from HAR’s published monthly reports. HAR reports townhomes and condominiums as one combined category; segment figures are directional and should not be used to value a specific unit or building. Lending guidelines change — confirm current project eligibility with your lender, and confirm association documents and statutory deadlines with your attorney. Nothing here is legal, tax, insurance, or lending advice. Informational only, no guarantee of outcomes.